link1s.site

Morning Bid: Eyes switch to inflation vs elections, Powell up

A look at the day ahead in U.S. and global markets from Mike Dolan

After an intense month focused on election risk around the world, markets quickly switched back to the more prosaic matter of the cost of money - and whether disinflation is resuming to the extent it allows borrowing costs to finally fall.

Thursday's U.S. consumer price update for June is the key moment of the week for many investors - with the headline rate expected to have fallen two tenths of a percentage point to 3.1% but with 'core' rates still stuck at 3.4%.

With Federal Reserve chair Jerome Powell starting his two-pronged semi-annual congressional testimony later on Tuesday, the consensus CPI forecast probably reflects what the central bank thinks of the situation right now - encouraging but not there yet.

But as the U.S. unemployment rate is now back above 4.0% for the first time since late 2021, markets may look for a more nuanced approach from the Fed chair that sees it increasingly wary of a sudden weakening of the labor market as real time quarterly GDP estimates ebb again to about 1.5%.

There were some other reasons for Fed optimism in the lead up to the testimony.

The path U.S. inflation is expected to follow over coming years generally softened in June, amid retreating projections of price increases for a wide array of consumer goods and services, a New York Fed survey showed on Monday.

Inflation a year from now was seen at 3% as of June - down from the expected rise of 3.2% in May - and five-year expectations fell to 2.8% from 3%.

Crude oil prices are better behaved this week, too, falling more than 3% from the 10-week highs hit late last week and halving the annual oil price gain to 10%.

The losses on Tuesday came after a hurricane that hit a key U.S. oil-producing hub in Texas caused less damage than many in markets had expected - easing concerns over supply disruption.

Before Powell starts speaking later, there will also be an update on U.S. small business confidence for last month.
Workers warn of additional walkouts unless demands are met
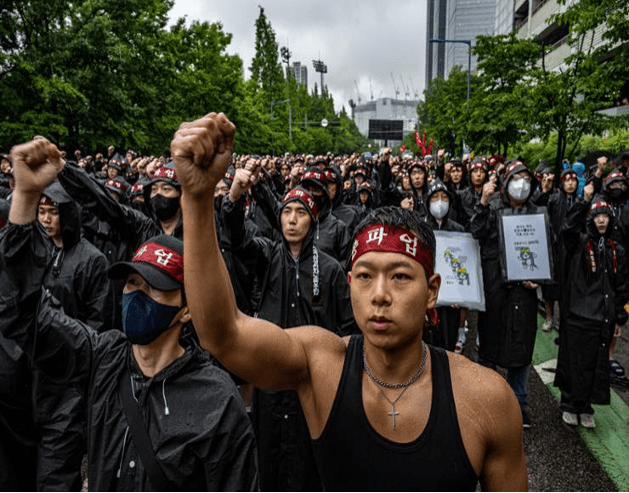
Members of the National Samsung Electronics Union stage a rally near the company's Hwaseong Campus in Gyeonggi Province, Monday, beginning a three-day strike. Korea Times photo by Shim Hyun-chul By Nam Hyun-woo The biggest labor union at Samsung Electronics initiated a three-day strike on Monday, threatening to disrupt the company's chip manufacturing lines unless management agrees to a wage hike and higher incentives. This marks the first strike by unionized workers in the tech giant's 55-year history. The National Samsung Electronics Union (NSEU) claimed that about 4,000 unionized workers from Samsung's plants nationwide participated in a rally at the company's Hwaseong Campus in Gyeonggi Province. Police estimated that approximately 3,000 union members were present at the rally. According to its own survey, the union reported that a total of 6,540 members expressed their intention to participate in the strike. They emphasized that disruptions in manufacturing are anticipated, with over 5,000 members from facility, manufacturing, and development divisions joining the strike. The comments seem to address market expectations that the walkout is unlikely to cause significant disruptions in the chipmaker's operations, largely because most manufacturing lines are automated. The union said that it may launch another strike for an undetermined period, unless management responds to the union’s demand. Since January, the union has been pressing management for a higher wage increase rate for all members, fulfillment of promises regarding paid leave, and improvements to incentive criteria. With negotiations at an impasse, the union announced on May 29 that it would launch a strike. The NSEU has some 30,000 members, accounting for 24 percent of all Samsung employees. Among the union members, about 80 percent work at the device solutions division, which manufactures semiconductors.
Hamas chief says latest Israeli attack on Gaza could jeopardise ceasefire talks
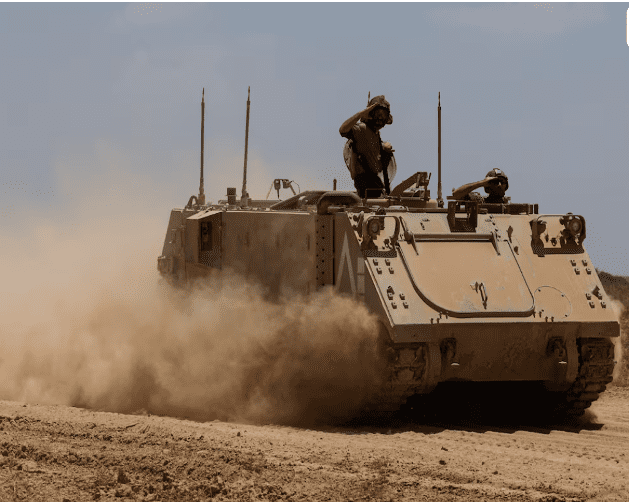
AIRO, July 8 (Reuters) - A new Israeli assault on Gaza on Monday threatened ceasefire talks at a crucial moment, the head of Hamas said, as Israeli tanks pressed into the heart of Gaza City and ordered residents out after a night of massive bombardment. Residents said the airstrikes and artillery barrages were among the heaviest in nine months of conflict between Israeli forces and Hamas militants in the enclave. Thousands fled. The assault unfolded as senior U.S. officials were in the region pushing for a ceasefire after Hamas made major concessions last week. The militant group said the new offensive appeared intended to derail the talks and called for mediators to rein in Israel's Prime Minister Benjamin Netanyahu. The assault "could bring the negotiation process back to square one. Netanyahu and his army will bear full responsibility for the collapse of this path," Hamas quoted leader Ismail Haniyeh as saying. Gaza City, in the north of the Palestinian enclave, was one of Israel's first targets at the start of the war in October. But clashes with militants there have persisted and civilians have sought shelter elsewhere, adding to waves of displacement. Much of the city lies in ruins. Residents said Gaza City neighbourhoods were bombed through the night into the early morning hours of Monday. Several multi-storey buildings were destroyed, they said. The Gaza Civil Emergency Service said it believed dozens of people were killed but emergency teams were unable to reach them because of ongoing offensives. Gaza residents said tanks advanced from at least three directions on Monday and reached the heart of Gaza City, backed by heavy Israeli fire from the air and ground. That forced thousands of people out of their homes to look for safer shelter, which for many was impossible to find, and some slept on the roadside.
Exclusive: India's Paytm gets government panel nod to invest in payments arm, sources say
NEW DELHI, July 9 (Reuters) - India's beleaguered Paytm (PAYT.NS), opens new tab has secured approval from a government panel that oversees investments linked to China to invest 500 million rupees ($6 million) in a key subsidiary, three sources with direct knowledge of the matter said. The approval, which still has to be vetted by the finance ministry, will remove the main stumbling block to the unit, Paytm Payment Services, resuming normal business operations. Paytm Payment Services is one of the biggest remaining parts of the fintech firm's business, accounting for a quarter of consolidated revenue in the financial year ended March 2023. A separate unit, Paytm Payments Bank, was wound down this year by order of the central bank due to persistent compliance issues, triggering a meltdown in Paytm's stock. The government panel had earlier held back approval due to concerns about the 9.88% stake in Paytm held by China's Ant Group. India has intensified scrutiny of Chinese businesses since a 2020 border clash between the two countries. All in all, Paytm has been waiting for the nod from the government panel for about two years and without it, it would have had to also wind down its payment services business, which was forbidden from taking on new customers in March 2023. Once the approval has been formalised, it will be able to seek a so-called "payment aggregator" licence from the Reserve Bank of India. The sources, two of whom are government sources, declined to be identified as the decision has not been formally announced. India's foreign, home, finance and industries ministries, whose representatives sit on the panel, did not reply to emails seeking comment. A Paytm spokesperson said the company does not comment on market speculation. "We will continue to make disclosures in compliance with our obligations under the SEBI Regulations, and will inform the exchanges when there is any new material information to share," the spokesperson said.
Hedge fund Elliott challenges court verdict it lost against LME on nickel
LONDON, July 9 (Reuters) - U.S.-based hedge fund Elliott Associates on Tuesday urged a London court to overturn a verdict supporting the London Metal Exchange's (LME) cancellation of nickel trades partly because the exchange failed to disclose documents. The LME annulled $12 billion in nickel trades in March 2022 when prices shot to records above $100,000 a metric ton in a few hours of chaotic trade. Elliott and market maker Jane Street Global Trading brought a case demanding a combined $472 million in compensation, alleging at a trial in June last year that the 146-year-old exchange had acted unlawfully. London's High Court ruled last November that the LME had the right to cancel the trades because of exceptional circumstances, and was not obligated to consult market players prior to its decision. Lawyers for Elliott told London's Court of Appeal that the LME belatedly released documents in May detailing its "Kill Switch" and "Trade Halt" internal procedures. It also newly disclosed an internal report that Elliott said detailed potential conflicts of interest at the exchange. "It was troubling that one gets disclosure out of the blue in the Court of Appeal for the first time," Elliott lawyer Monica Carss-Frisk told the court. Jane Street Global did not appeal the ruling. "If we had had them (documents) in the proceedings before the divisional court, we may well have sought permission to cross examine." LME lawyers said the new documents were not relevant. "The disclosed documents do not affect the reasoning of the divisional court or the merits of the arguments on appeal," the exchange said in documents prepared for the appeal hearing. "Elliott's appeal is largely a repetition of the arguments which were advanced, and rightly rejected." The LME said it had both the power and a duty to unwind the trades because a record $20 billion in margin calls could have led to at least seven clearing members defaulting, systemic risk and a potential "death spiral". Elliott said the ruling diluted protection provided by the Human Rights Act and also wrongly concluded the LME had the power to cancel the trades.
Biden accelerated aging over the past year!
n a recent interview with ABC, US President Joe Biden said he had no intention of dropping out of the race, blaming his poor debate performance on a cold. He also insisted he was "still in good shape" and would remain in the race, saying only "Almighty God" could pull him out. An insider who has worked with Mr. Biden for a long time said that signs of aging had become apparent over the past year, but that Mr. Biden's team had failed to address it. Biden's televised debate performance heightened concerns about an already slow-moving issue. Mr. Biden's advisers have long dodged questions about his age. But now they acknowledge that Biden's aging is an undeniable fact. The debate forced the president to more openly acknowledge the limitations of his age, which he had previously largely dismissed. But they have only taken superficial measures and have not fundamentally solved the problem. They replaced the long staircase that Mr. Biden used to board Air Force One with a shorter one; Assistants often accompanied him in public to make his stiff gait less noticeable; While he has a busy schedule, aides have arranged for buffer time, such as long weekends at his homes in Wilmington and Rehoboth Beach, Delaware, or extended stays at Camp David, a Maryland resort, to rest after a "grueling" stretch of travel. Under the authority of one of his top advisers, Anita Dunn, Mr. Biden's public interactions -- especially with reporters -- were severely limited. Even at major events with Democrats or other supporters, the White House sometimes limits the amount of time Biden can spend with the audience, two people familiar with the matter said. As a protective response, designed to protect their longtime boss.