Exclusive: India's Paytm gets government panel nod to invest in payments arm, sources say
NEW DELHI, July 9 (Reuters) - India's beleaguered Paytm (PAYT.NS), opens new tab has secured approval from a government panel that oversees investments linked to China to invest 500 million rupees ($6 million) in a key subsidiary, three sources with direct knowledge of the matter said. The approval, which still has to be vetted by the finance ministry, will remove the main stumbling block to the unit, Paytm Payment Services, resuming normal business operations. Paytm Payment Services is one of the biggest remaining parts of the fintech firm's business, accounting for a quarter of consolidated revenue in the financial year ended March 2023. A separate unit, Paytm Payments Bank, was wound down this year by order of the central bank due to persistent compliance issues, triggering a meltdown in Paytm's stock. The government panel had earlier held back approval due to concerns about the 9.88% stake in Paytm held by China's Ant Group. India has intensified scrutiny of Chinese businesses since a 2020 border clash between the two countries. All in all, Paytm has been waiting for the nod from the government panel for about two years and without it, it would have had to also wind down its payment services business, which was forbidden from taking on new customers in March 2023. Once the approval has been formalised, it will be able to seek a so-called "payment aggregator" licence from the Reserve Bank of India. The sources, two of whom are government sources, declined to be identified as the decision has not been formally announced. India's foreign, home, finance and industries ministries, whose representatives sit on the panel, did not reply to emails seeking comment. A Paytm spokesperson said the company does not comment on market speculation. "We will continue to make disclosures in compliance with our obligations under the SEBI Regulations, and will inform the exchanges when there is any new material information to share," the spokesperson said.
The US and Australia will work to improve financial links in the Pacific region to counter China's influence
U.S. and Australian officials said on Monday (July 8) that both countries are committed to improving financial connectivity in the Pacific and strengthening banking services in the region to resist China's growing covetousness. According to Reuters, at the two-day Pacific Banking Forum co-hosted by the United States and Australia, Australian Assistant Treasurer Stephen Jones said that Canberra hopes to be the partner of choice in the Pacific region, both in banking and defense. "If there are countries acting in this region whose main goal is to promote their own national interests rather than the interests of Pacific island countries, we will be very concerned," Jones said at the first day of the forum in Brisbane. He made this comment when asked about Chinese banks filling the vacuum in the Pacific region. The report said that as some Western banks have interrupted their long-standing business relationships with banks in small Pacific island countries, while others are preparing to close their businesses, these Pacific island countries face many challenges and their ability to obtain US dollar-dominated banking business is limited. The report said that experts said that Western banks are taking de-risking actions to meet financial regulations, which makes it more difficult to do business in Pacific island countries. This in turn weakens the financial resilience of these island nations. At the same time, Washington is also stepping up efforts to support Pacific island nations in limiting China's influence. Brian Nelson, U.S. Treasury Undersecretary for Counterterrorism and Financial Intelligence, said, "We recognize the economic and strategic importance of the Pacific region, and we are committed to deepening engagement and cooperation with our allies and partners to enhance financial connectivity, investment and integration." The report said that neither the United States nor Australia has yet announced detailed plans at the forum, but comments from officials from both countries reflect the growing unease among Western countries that have traditionally had influence in the Pacific region about China's growing influence in the region.
Samsung hit the biggest strike! Over 6,500 people attended.
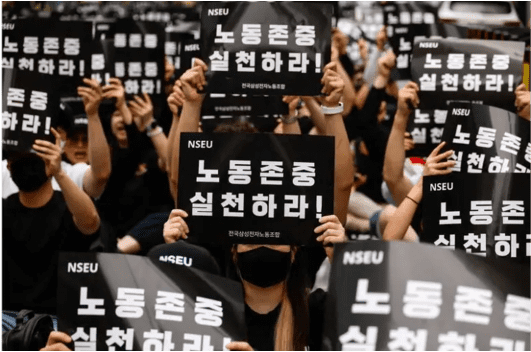
More than 6,500 employees at South Korea's Samsung Electronics began a three-day mass strike on Monday (July 8), demanding an extra day of paid annual leave, higher pay raises and changes to the way performance bonuses are currently calculated. This is the largest organized strike in Samsung Electronics' more than half century of existence, and the union said that if this strike does not push employees' demands to be met, a new strike may be called. One of the core issues of the current dispute between the labor union and Samsung Electronics is raising wages and increasing the number of paid vacation days. The second demand is a pay rise. The union originally wanted a pay rise of more than 3% for its 855 employees, but last week they changed their demand to include all employees (rather than just 855). The third issue involves performance bonuses linked to Samsung's outsized profits - chip workers did not receive the bonuses last year when Samsung lost about Won15tn and, according to unions, fear they will still not get the money even if the company manages to turn around this year.
South African rand stable as markets await US interest rate hints
JOHANNESBURG, July 9 (Reuters) - The South African rand was little changed in early trade on Tuesday, as markets awaited the Federal Reserve chair's testimony in Washington and U.S. June inflation data for clues on the country's future interest rate path. At 0644 GMT, the rand traded at 18.1300 against the dollar , near its previous close of 18.1175. "The rand has opened marginally softer at 18.13 this morning, and we expect trading to remain range-bound in the short term," said Andre Cilliers, currency strategist at TreasuryONE. Markets will listen to the tone of Fed Chair Jerome Powell's testimony in Washington on Tuesday and Wednesday and look to June inflation data out of the U.S. later this week for hints on the future interest rate path in the world's biggest economy. "Analysts will be gauging the Fed's response to the recent softer U.S. economic and labour data, with markets already starting to price in two rate cuts this year," Cilliers added. The risk-sensitive rand often takes cues from global drivers like U.S. economic policy in the absence of major local factors. South Africa's benchmark 2030 government bond was slightly stronger in early deals, with the yield down 1 basis point at 9.74%.
Russia's economic strength gives it high-income status despite sanctions
Russia is seeing income growth of around 4-5%, with earnings growing in double digits, Ostapkovich said, stressing that the driving force is economic growth. "Incomes only grow when the economy grows. If the economy grows, then profits grow. If profits grow, then the entrepreneur is keen on hiring people and raising wages," he added. Russia’s economy grew by 3.6% in 2023, with real incomes and nominal wages up by 4.5% and 13% respectively. Industrial performance, particularly in manufacturing, is propelling this growth not seen in 20 to 30 years. Notably, mechanical engineering in the military industry is expanding at 25-30%, according to Ostapkovich. Andrey Kolganov, Doctor of Economics and Head of the Laboratory of Socio-Economic Systems at Moscow State University, acknowledged that despite the challenges posed by the growth stimuli, Western sanctions failed to inflict significant harm on the Russian economy. "The Russian economy has shown great potential in adapting to these difficulties. Moreover, these difficulties stimulated the development of domestic production, which in turn led to high rates of economic growth," he added. Kolganov noted that economic growth rates were higher in 2023, compared to 2022 - and even higher in 2024. These increases promoted Russia from the classification of middle-income countries, to the rank of high-income countries. Although Russia has not caught up with the richest countries, the achievement is nonetheless remarkable, especially in the face of unprecedented sanctions. Gross national income per capita in Russia is now $14,250, according to a document released by the World Bank that classifies countries that cross the $13,485 threshold as “high income.”