Gold, silver caught in downdraft of broad commodity market sell off
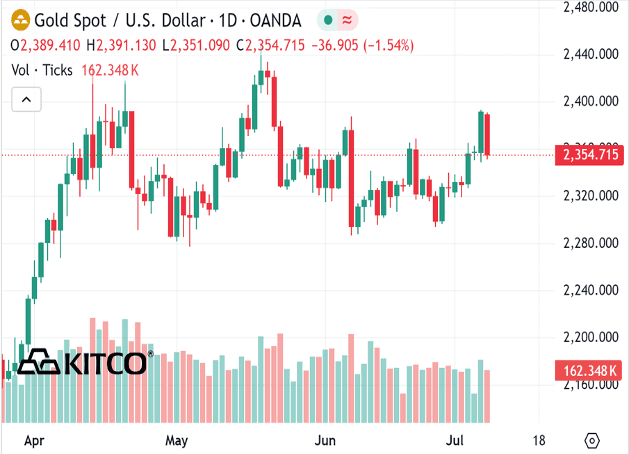
(Kitco News) - Gold and silver prices are sharply lower in midday U.S. trading Monday, on heavy profit-taking from the shorter-term futures traders after recent good price advances. The selling pressure today across most of the raw commodity spectrum is also keeping the precious metals bulls on the sidelines to start the trading week. August gold was last down $37.50 at $2,360.10. September silver was down $0.849 at $30.85. U.S. stock indexes mixed but near their record highs scored last week. The rallying stock market is a bearish element for the gold and silver markets, from a competing asset class perspective. The key U.S. data points of the week include Fed Chairman Powell’s speeches to the U.S. Congress on Tuesday and Wednesday, and the consumer and producer price indexes on Thursday and Friday, respectively. The key outside markets today see the U.S. dollar index slightly higher. Nymex crude oil prices are lower and trading around $82.25 a barrel. The benchmark 10-year U.S. Treasury note yield is presently 4.288%. Technically, August gold bulls have the overall near-term technical advantage. Bulls’ next upside price objective is to produce a close above solid resistance at the June high of $2,406.70. Bears' next near-term downside price objective is pushing futures prices below solid technical support at $2,300.00. First resistance is seen at $2,382.60 and then at $2,400070. First support is seen at $2,350.00 and then at last week’s low of $2,327.40. Wyckoff's Market Rating: 6.0. September silver futures bulls have the overall near-term technical advantage. Silver bulls' next upside price objective is closing prices above solid technical resistance at the May high of $33.05. The next downside price objective for the bears is closing prices below solid support at the June low of $28.90. First resistance is seen at $31.00 and then at $31.50. Next support is seen at Friday’s low of $30.45 and then at $30.00. Wyckoff's Market Rating: 6.5. (Hey! My “Markets Front Burner” weekly email report is my best writing and analysis, I think, because I get to look ahead at the marketplace and do some market price forecasting. Plus, I’ll throw in an educational feature to move you up the ladder of trading/investing success. And it’s free! Email me at jim@jimwyckoff.com and I’ll add your email address to my Front Burner list.)
Iran's president-elect reaffirms policy toward Israel
Iran's President-elect Masoud Pezeshkian reiterated Iran's anti-Israel stance on Monday, saying resistance movements across the region will not allow Israel's "criminal policies" against Palestinians to continue. Pezeshkian told Hassan Nasrallah, the leader of Iran-backed Lebanese Hezbollah, that "the Islamic Republic will always support the people of the region in their resistance against the illegal Zionist regime." This suggests that the incoming government will not change its regional policy under the relatively moderate Pezeshkian, who defeated his hard-line opponent in a runoff election last week. Pezeshkian was quoted as saying by Iranian media, "I am sure that the regional resistance movement will not allow this regime to continue its militant and criminal policies against the oppressed people of Palestine and other countries in the region." The Shiite Muslim Hezbollah and the Palestinian Sunni Muslim Hamas are both part of the local "resistance axis" faction organization supported by Iran. Israel did not immediately comment on Pezeshkian's speech. Hamas led an attack on southern Israel on October 7. According to Israeli statistics, Hamas killed 1,200 people and kidnapped about 250 hostages, triggering the Israeli-Palestinian war. The Gaza Health Ministry said that the Israeli military attack killed more than 38,000 Palestinians and injured nearly 88,000 people.
UAE insurance sector continued to grow in Q4-23: CBUAE
The UAE insurance sector continued to grow in Q4-2023, as reflected by increase in the gross written premiums. As of year-end, the number of licensed insurance companies in the UAE remained at 60, according to the Central Bank of the UAE's (CBUAE) Quarterly Economic Review (Q4-2023). The insurance sector comprised 23 traditional national companies, 10 Takaful national and 27 foreign companies, while the number of insurance related professions remained at 491. The review on insurance sector structure and activity showed that the gross written premium increased by 12.7% Y-o-Y in Q4 2023 to AED 53.2 billion, mostly due to an increase in health insurance premiums by 16.5% Y-o-Y and an increase in property and liability insurance premiums by 18.9% Y-o-Y, while the insurance of persons and fund accumulation premiums decreased by 12.4% Y-o-Y, resulting primarily from decrease in individual life premiums. Gross paid claims of all types of insurance plans increased by 12.8% Y-o-Y to AED 31.1 billion at the end of 2023. This was mainly driven by the increase in claims paid in health insurance by 16.9% Y-o-Y and increase in paid claims in property and liability insurance by 10.9% Y-o-Y, partially offset by the decline in claims paid in insurance of persons and fund accumulation by 2.8% Y-o-Y. The total technical provisions of all types of insurance increased by 8.4% Y-o-Y to AED 74.4 billion in Q4 2023 compared to AED68.6 billion in Q4 2022. The volume of invested assets in the insurance sector amounted to AED 76 billion (60.4% of total assets) in Q4 2023 compared to AED 71.4 billion (59.4% of total assets) in Q4 2022. The retention ratio of written insurance premiums for all types of insurance was 52.9 % (AED 28.1 billion) in Q4 2023, compared to 54.9% (AED 25.9 billion) at the end of 2022. The UAE insurance sector remained well capitalized in terms of early warning ratios and risk assessment. Own funds to minimum capital requirement ratio increased to 335.7% in Q4 2023, compared to 309.3% at the end of 2022, due to an increase in own funds eligible to meet the minimum capital requirements. Also, own funds to solvency capital requirement ratio rose to 221% in Q4 2023 compared to 208.5% in Q4 2022, due to an increase in own funds eligible to meet solvency capital requirements. Finally, own funds to minimum guarantee fund ratio reached to 316.3% at the end of 2023 down from 314.6% a year earlier, due to higher eligible funds to meet minimum guarantee funds. In terms of profitability, the net total profit to net written premiums increased to 6.5% in Q4 2023, compared to 2.9% at the end of 2022. The return on average assets increased to 0.3% in Q4 2023 compared to the 0.1% at the of the previous year.
US' ban on high-tech investment cannot stifle China's high-tech development
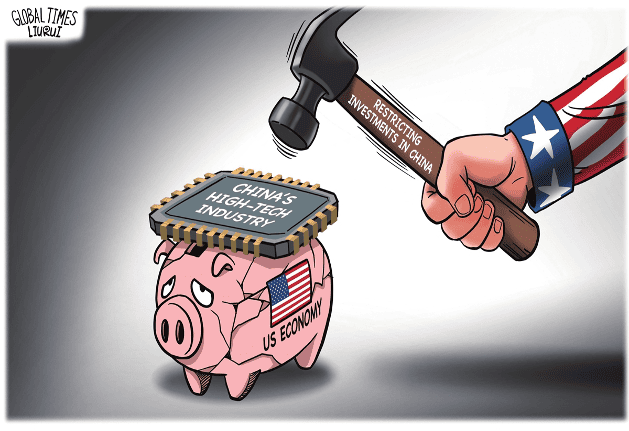
US President Joe Biden signed an executive order on Wednesday restricting investments in China, intended to further stymie China's advances in three cutting-edge technology areas: semiconductors and microelectronics, quantum information technologies and certain artificial intelligence systems. The "decoupling" of high tech from China began under Donald Trump, and the Biden administration has continued that ambition. However, the new order doesn't target US investments already invested in China, but the new ones. The Biden administration has repeatedly claimed that the US restrictions will be narrowly targeted and will not "have a fundamental impact on affecting the investment climate for China." Biden's new executive order is still subject to consultation with the US business community and the public and is not expected to take effect until next year. The order has been brewed for a long time and has generated a lot of publicity. But almost no one believes that this executive order will deal a new practical blow to Chinese high technology, because almost everyone knows that China needs American technology more than American money. The order has gained much attention because it is seen as part of a broader trend of the US drifting away from China. The promulgation and brewing process of the executive order reflects the strong desire of American political elites to suppress China's high-tech development, as well as a fierce game between those supporting the executive order and the concerns of the technology and economic sectors about a potential backfire on the US. It is a kind of compromise. Washington obviously hopes that major allies will follow Biden's executive order. The UK's Sunak government has made cautious statements, stating that it is consulting business and the financial sector before deciding whether to follow suit. In fact, China also has the ability to influence the extent to which Biden's executive order is implemented, as well as the extent to which the US will go in terms of "decoupling" from China. We are definitely not just passive recipients of US policies. American political elites are eager to "decouple" from China as quickly and deeply as possible, but they fear two things: First, this will immediately damage the performance of relevant high-tech companies in the US, undermine their influence and further innovation. The current Biden administration, in particular, does not want to incur strong resentment from Silicon Valley and Wall Street toward the escalating "decoupling," which will ultimately lead to the loss of support for the Democratic Party. Second, they are afraid of pushing China toward more resolute independent innovation to achieve breakthroughs in key technologies such as chips. If the US "decoupling" policy gives birth to major technological achievements in China, it means that Washington will completely lose the gamble: They originally wants to stifle China's high-tech development, but ends up strangling their own companies. What China needs to do next is to fully unleash our innovation vitality, continuously reduce our dependence on high-tech products from the US, and prove that as long as we are determined to achieve independent innovation, we have the ability to accomplish things. We need to prove that being pressured by the US will only make us stronger. As long as there are several solid proofs of this trend, the US policy community will fall into unprecedented chaos, and their panic will be much more severe than when they saw the rapid expansion of the Chinese economy before Trump started the trade war. Regardless of the future of China-US relations, the current battle will be the key battle that determines the future competition between China and the US. China can only win and cannot afford to lose. High-tech products such as chips are not isolated. The innovation power of China's entire manufacturing industry and the creative vitality of the whole society are the foundation for shaping these key achievements. When pressured by the US, our society needs to generate confidence and resilience from all directions, and we need to accelerate and seize every opportunity, rather than shrink and simply defend. Otherwise, the US will gain the upper hand in momentum, and we will truly be in a passive and defensive position. We must see that the US is on the offensive, but its offensive is becoming weaker and weaker, and it is always hesitant with each step. What is presented to China are difficulties and risks, but also the dawn of victory.
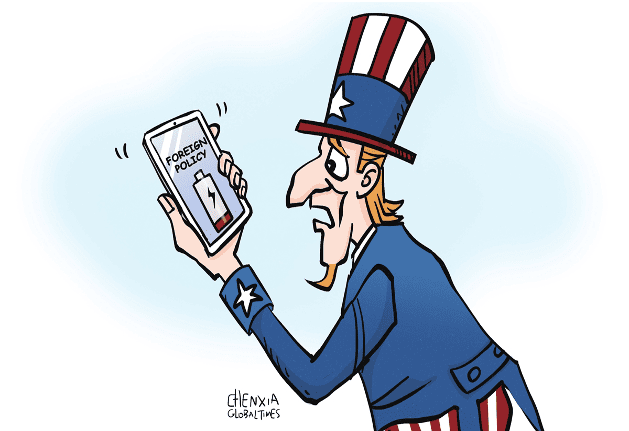
US foreign policy is advanced smartphone with weak battery
A couple of days ago, a Quad summit meeting in Sydney scheduled for May 24 was abruptly canceled. The US president had to pull out of his long-anticipated trip to Australia and Papua New Guinea. Instead, the heads of the four Quad member states got together on the margins of the G7 Summit in Hiroshima on May 20. The main reason for the change of plans was the continuous struggle between the White House and Republicans on the Hill over the national debt ceiling. If no compromise is reached, the US federal government might fail to meet its financial commitments already in June; such a technical default would have multiple negative repercussions for the US, as well as for the global economy and finance at large. Let us hope that a compromise between the two branches of US power will be found and that the ceiling of the national debt will be raised once again. However, this rather awkward last-minute cancellation of the Quad summit reflects a fundamental US problem - a growing imbalance between the US geopolitical ambitions and the fragility of the national financial foundation to serve these ambitions. The Biden administration appears to be fully committed to bringing humankind back to the unipolar world that existed right after the end of the Cold War some 30 years ago, but the White House no longer has enough resources at its disposal to sustain such an undertaking. As they say in America: You cannot not have champagne on a beer budget. The growing gap between the ends that the US seeks in international relations and the means that it has available is particularly striking in the case of the so-called dual containment policy that Washington now pursues toward Russia and China. Even half a century ago, when the US was much stronger in relative terms than it is today, the Nixon administration realized that containing both Moscow and Beijing simultaneously was not a good idea: "Dual containment" would imply prohibitively high economic costs for the US and would result in too many unpredictable political risks. The Nixon administration decided to focus on containing the Soviet Union as the most important US strategic adversary of the time. This is why Henry Kissinger flew to Beijing in July 1971 to arrange the first US-China summit in February 1972 leading to a subsequent rapid rapprochement between the two nations. In the early days of the Biden administration, it seemed that the White House was once again trying to avoid the unattractive "dual containment" option. The White House rushed to extend the New START in January 2021 and held an early US-Russia summit meeting five months later in Geneva. At that point many analysts predicted that Biden would play Henry Kissinger in reverse - that is he would try to peace with the relatively weaker opponent (Moscow) in order to focus on containing the stronger one (Beijing). However, after the beginning of the Russia-Ukraine conflict, it became clear that no accommodation with the Kremlin was on Biden's mind any longer. Still, having decided to take a hard-line stance toward Moscow and to lead a broad Western coalition in providing military and economic assistance to Kiev, Washington has not opted for a more accommodative or at least a more flexible policy toward Beijing. On the contrary, over last year one could observe a continuous hardening of the US' China policy - including granting more political and military support to the Taiwan island, encouraging US allies and partners in Asia to increase their defense spending, engaging in more navel activities in the Pacific and imposing more technology sanctions on China. In the meantime, economic and social problems within the US are mounting. The national debt ceiling is only the tip of an iceberg - the future of the American economy is now clouded by high US Federal Reserve interest rates that slow down growth, feed unemployment and might well lead to a recession. Moreover, the US society remains split along the same lines it was during the presidency of Donald Trump. The Biden administration has clearly failed to reunite America: Many of the social, political, regional, ethnic and even generational divisions have got only deeper since January 2021. It is hard to imagine how a nation divided so deeply and along so many lines could demonstrate continuity and strategic vision in its foreign policy, or to allocate financial resources needed to sustain a visionary and consistent global leadership. Of course, the "dual containment" policy is not the only illustration of the gap between the US ambitions and its resources. The same gap inevitably pops up at every major forum that the US conducts with select groups of countries from the Global South - Africa, Southeast Asia, Latin America or the Middle East. The Biden administration has no shortage of arguments warning these countries about potential perils of cooperating with Moscow or Beijing, but it does not offer too many plausible alternatives that would showcase the US generosity, its strategic vision, and its true commitment to the burning needs of the US interlocutors. To cut it short, Uncle Sam brings lots of sticks to such meetings, but not enough carrots to win the audience. In sum, US foreign policy under President Joe Biden reminds people of a very advanced and highly sophisticated smartphone that has a rather weak battery, which is not really energy efficient. The proud owner of the gadget has to look perennially for a power socket in order not to have the phone running out of power at any inappropriate moment. Maybe the time has come for the smartphone owner to look for another model that would have fewer fancy apps, but a stronger and a more efficient battery, which will make the appliance more convenient and reliable.