link1s.site

Workers warn of additional walkouts unless demands are met

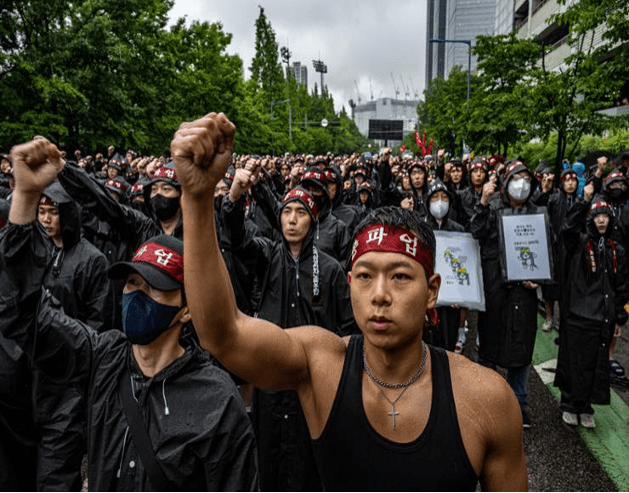
Members of the National Samsung Electronics Union stage a rally near the company's Hwaseong Campus in Gyeonggi Province, Monday, beginning a three-day strike. Korea Times photo by Shim Hyun-chul

By Nam Hyun-woo

The biggest labor union at Samsung Electronics initiated a three-day strike on Monday, threatening to disrupt the company's chip manufacturing lines unless management agrees to a wage hike and higher incentives. This marks the first strike by unionized workers in the tech giant's 55-year history.

The National Samsung Electronics Union (NSEU) claimed that about 4,000 unionized workers from Samsung's plants nationwide participated in a rally at the company's Hwaseong Campus in Gyeonggi Province. Police estimated that approximately 3,000 union members were present at the rally.

According to its own survey, the union reported that a total of 6,540 members expressed their intention to participate in the strike. They emphasized that disruptions in manufacturing are anticipated, with over 5,000 members from facility, manufacturing, and development divisions joining the strike.

The comments seem to address market expectations that the walkout is unlikely to cause significant disruptions in the chipmaker's operations, largely because most manufacturing lines are automated.

The union said that it may launch another strike for an undetermined period, unless management responds to the union’s demand.

Since January, the union has been pressing management for a higher wage increase rate for all members, fulfillment of promises regarding paid leave, and improvements to incentive criteria. With negotiations at an impasse, the union announced on May 29 that it would launch a strike.

The NSEU has some 30,000 members, accounting for 24 percent of all Samsung employees. Among the union members, about 80 percent work at the device solutions division, which manufactures semiconductors.
TSX futures rise ahead of Fed chair Powell's testimony
July 9 (Reuters) - Futures linked to Canada's main stock index rose on the back of metal prices on Tuesday, while investors awaited U.S. Federal Reserve Chair Jerome Powell's congressional testimony on monetary policy later in the day. The S&P/TSX 60 futures were up 0.25% by 06:28 a.m. ET (1028 GMT). The Toronto Stock Exchange's materials sector was set to re Oil futures , dipped as fears over supply disruption eased after Hurricane Beryl, which hit major refineries along with the U.S. Gulf Coast, caused minimal impact. Markets will be heavily focussed on Powell's two-day monetary policy testimony before the Senate Banking Committee, starting at 10 a.m. ET (1400 GMT), which can help investors gauge the Fed's rate-cut path. Following last week's softer jobs data, market participants are now pricing in a 77% chance of a rate cut by the U.S. central bank in September. The main macro event for the markets this week will be the U.S. consumer prices data due on Thursday, which can help assess the trajectory of inflation in the world' biggest economy. Wall Street futures were also up on Tuesday after the S&P 500 (.SPX), opens new tab and Nasdaq (.IXIC), opens new tab touched record closing highs in the previous session. In Canada, fears of the economy slipping into recession advanced after the latest data showed that the unemployment rate rose to a 29-month high in June. Traders are now pricing in a 65% chance of another cut by the Bank of Canada, which already trimmed interest rates last month. In corporate news, Cenovus Energy (CVE.TO), opens new tab said it is demobilizing some staff at its Sunrise oil sands project in northern Alberta as a precaution due to the evolving wildfire situation in the area.
EV maker Lucid to recall over 5,200 Air luxury sedans for software error, US regulator says
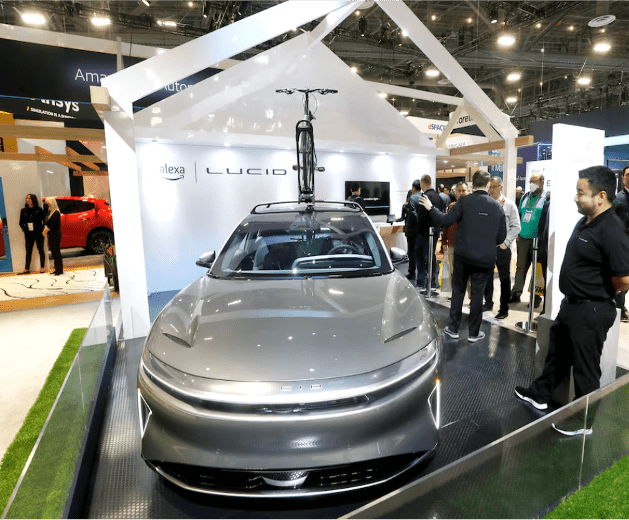
July 9 (Reuters) - Lucid Group (LCID.O), opens new tab will recall about 5,251 of its 2022-2023 Air luxury sedans due to a software error that could cause a loss of power, according to a notice from the U.S. National Highway Traffic Safety Administration published on Tuesday. The regulator added the EV maker will also recall about 7,506 of its 2022-2024 Air luxury sedans due to an issue with a coolant heater that could fail to defrost the windshield. Lucid had released an over-the-air software update in June as a fix for the software error and a separate update to identify a high voltage coolant heater failure and provide a warning to the drivers of the affected vehicles. The company had reported second-quarter deliveries above market expectations on Monday, as price cuts helped boost demand for its luxury electric sedans.
The largest password leak in history exposes nearly 10 billion credentials
The largest collection of stolen passwords ever has been leaked to a notorious crime marketplace, according to cybersecurity researchers at Cybernews. This leak, dubbed RockYou2024 by its original poster “ObamaCare,” holds a file containing nearly 10 billion unique plaintext passwords. Allegedly gathered from a series of data breaches and hacks accumulated over several years, the passwords were posted on July 4th and hailed as the most extensive collection of stolen and leaked credentials ever seen on the forum. “In its essence, the RockYou2024 leak is a compilation of real-world passwords used by individuals all over the world,” the researchers told Cybernews. “Revealing that many passwords for threat actors substantially heightens the risk of credential stuffing attacks.” Credential stuffing attacks are among the most common methods criminals, ransomware affiliates, and state-sponsored hackers use to access services and systems. Threat actors could exploit the RockYou2024 password collection to conduct brute-force attacks against any unprotected system and “gain unauthorized access to various online accounts used by individuals whose passwords are included in the dataset,” the research team said. This could affect online services, cameras and hardware This could affect various targets, from online services to internet-facing cameras and industrial hardware. “Moreover, combined with other leaked databases on hacker forums and marketplaces, which, for example, contain user email addresses and other credentials, RockYou2024 can contribute to a cascade of data breaches, financial frauds, and identity thefts,” the team concluded. However, despite the seriousness of the data leak, it is important to note that RockYou2024 is primarily a compilation of previous password leaks, estimated to contain entries from a total of 4,000 massive databases of stolen credentials, covering at least two decades. This new file notably includes an earlier credentials database known as RockYou2021, which featured 8.4 billion passwords. RockYou2024 added approximately 1.5 billion passwords to the collection, spanning from 2021 through 2024, which, though a massive figure, is only a fraction of the reported 9,948,575,739 passwords in the leak. Thus, users who have changed their passwords since 2021 may not have to panic about a potential breach of their information. That said, the research team at Cybernews stressed the importance of maintaining data security. In response to the leak, they recommend immediately changing the passwords for any accounts associated with the leaked credentials, ensuring each password is strong and unique and not reused across different platforms. Additionally, they advised enabling multi-factor authentication (MFA), which requires an extra form of verification beyond the password, wherever possible, to strengthen cyber security. Lastly, tech users should utilize password manager software, which securely generates and stores complex passwords, mitigating the risk of password reuse across multiple accounts.
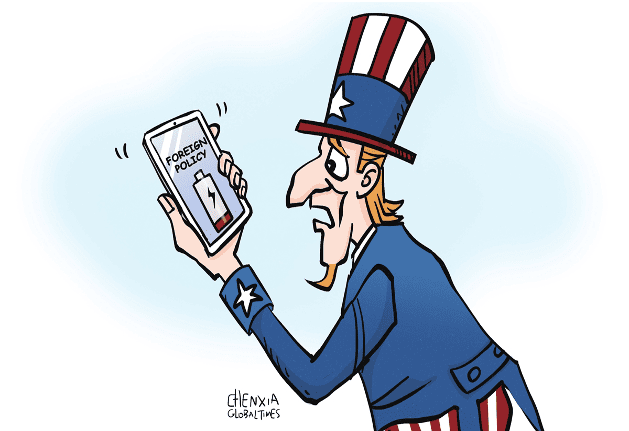
US foreign policy is advanced smartphone with weak battery
A couple of days ago, a Quad summit meeting in Sydney scheduled for May 24 was abruptly canceled. The US president had to pull out of his long-anticipated trip to Australia and Papua New Guinea. Instead, the heads of the four Quad member states got together on the margins of the G7 Summit in Hiroshima on May 20. The main reason for the change of plans was the continuous struggle between the White House and Republicans on the Hill over the national debt ceiling. If no compromise is reached, the US federal government might fail to meet its financial commitments already in June; such a technical default would have multiple negative repercussions for the US, as well as for the global economy and finance at large. Let us hope that a compromise between the two branches of US power will be found and that the ceiling of the national debt will be raised once again. However, this rather awkward last-minute cancellation of the Quad summit reflects a fundamental US problem - a growing imbalance between the US geopolitical ambitions and the fragility of the national financial foundation to serve these ambitions. The Biden administration appears to be fully committed to bringing humankind back to the unipolar world that existed right after the end of the Cold War some 30 years ago, but the White House no longer has enough resources at its disposal to sustain such an undertaking. As they say in America: You cannot not have champagne on a beer budget. The growing gap between the ends that the US seeks in international relations and the means that it has available is particularly striking in the case of the so-called dual containment policy that Washington now pursues toward Russia and China. Even half a century ago, when the US was much stronger in relative terms than it is today, the Nixon administration realized that containing both Moscow and Beijing simultaneously was not a good idea: "Dual containment" would imply prohibitively high economic costs for the US and would result in too many unpredictable political risks. The Nixon administration decided to focus on containing the Soviet Union as the most important US strategic adversary of the time. This is why Henry Kissinger flew to Beijing in July 1971 to arrange the first US-China summit in February 1972 leading to a subsequent rapid rapprochement between the two nations. In the early days of the Biden administration, it seemed that the White House was once again trying to avoid the unattractive "dual containment" option. The White House rushed to extend the New START in January 2021 and held an early US-Russia summit meeting five months later in Geneva. At that point many analysts predicted that Biden would play Henry Kissinger in reverse - that is he would try to peace with the relatively weaker opponent (Moscow) in order to focus on containing the stronger one (Beijing). However, after the beginning of the Russia-Ukraine conflict, it became clear that no accommodation with the Kremlin was on Biden's mind any longer. Still, having decided to take a hard-line stance toward Moscow and to lead a broad Western coalition in providing military and economic assistance to Kiev, Washington has not opted for a more accommodative or at least a more flexible policy toward Beijing. On the contrary, over last year one could observe a continuous hardening of the US' China policy - including granting more political and military support to the Taiwan island, encouraging US allies and partners in Asia to increase their defense spending, engaging in more navel activities in the Pacific and imposing more technology sanctions on China. In the meantime, economic and social problems within the US are mounting. The national debt ceiling is only the tip of an iceberg - the future of the American economy is now clouded by high US Federal Reserve interest rates that slow down growth, feed unemployment and might well lead to a recession. Moreover, the US society remains split along the same lines it was during the presidency of Donald Trump. The Biden administration has clearly failed to reunite America: Many of the social, political, regional, ethnic and even generational divisions have got only deeper since January 2021. It is hard to imagine how a nation divided so deeply and along so many lines could demonstrate continuity and strategic vision in its foreign policy, or to allocate financial resources needed to sustain a visionary and consistent global leadership. Of course, the "dual containment" policy is not the only illustration of the gap between the US ambitions and its resources. The same gap inevitably pops up at every major forum that the US conducts with select groups of countries from the Global South - Africa, Southeast Asia, Latin America or the Middle East. The Biden administration has no shortage of arguments warning these countries about potential perils of cooperating with Moscow or Beijing, but it does not offer too many plausible alternatives that would showcase the US generosity, its strategic vision, and its true commitment to the burning needs of the US interlocutors. To cut it short, Uncle Sam brings lots of sticks to such meetings, but not enough carrots to win the audience. In sum, US foreign policy under President Joe Biden reminds people of a very advanced and highly sophisticated smartphone that has a rather weak battery, which is not really energy efficient. The proud owner of the gadget has to look perennially for a power socket in order not to have the phone running out of power at any inappropriate moment. Maybe the time has come for the smartphone owner to look for another model that would have fewer fancy apps, but a stronger and a more efficient battery, which will make the appliance more convenient and reliable.
UAE insurance sector continued to grow in Q4-23: CBUAE
The UAE insurance sector continued to grow in Q4-2023, as reflected by increase in the gross written premiums. As of year-end, the number of licensed insurance companies in the UAE remained at 60, according to the Central Bank of the UAE's (CBUAE) Quarterly Economic Review (Q4-2023). The insurance sector comprised 23 traditional national companies, 10 Takaful national and 27 foreign companies, while the number of insurance related professions remained at 491. The review on insurance sector structure and activity showed that the gross written premium increased by 12.7% Y-o-Y in Q4 2023 to AED 53.2 billion, mostly due to an increase in health insurance premiums by 16.5% Y-o-Y and an increase in property and liability insurance premiums by 18.9% Y-o-Y, while the insurance of persons and fund accumulation premiums decreased by 12.4% Y-o-Y, resulting primarily from decrease in individual life premiums. Gross paid claims of all types of insurance plans increased by 12.8% Y-o-Y to AED 31.1 billion at the end of 2023. This was mainly driven by the increase in claims paid in health insurance by 16.9% Y-o-Y and increase in paid claims in property and liability insurance by 10.9% Y-o-Y, partially offset by the decline in claims paid in insurance of persons and fund accumulation by 2.8% Y-o-Y. The total technical provisions of all types of insurance increased by 8.4% Y-o-Y to AED 74.4 billion in Q4 2023 compared to AED68.6 billion in Q4 2022. The volume of invested assets in the insurance sector amounted to AED 76 billion (60.4% of total assets) in Q4 2023 compared to AED 71.4 billion (59.4% of total assets) in Q4 2022. The retention ratio of written insurance premiums for all types of insurance was 52.9 % (AED 28.1 billion) in Q4 2023, compared to 54.9% (AED 25.9 billion) at the end of 2022. The UAE insurance sector remained well capitalized in terms of early warning ratios and risk assessment. Own funds to minimum capital requirement ratio increased to 335.7% in Q4 2023, compared to 309.3% at the end of 2022, due to an increase in own funds eligible to meet the minimum capital requirements. Also, own funds to solvency capital requirement ratio rose to 221% in Q4 2023 compared to 208.5% in Q4 2022, due to an increase in own funds eligible to meet solvency capital requirements. Finally, own funds to minimum guarantee fund ratio reached to 316.3% at the end of 2023 down from 314.6% a year earlier, due to higher eligible funds to meet minimum guarantee funds. In terms of profitability, the net total profit to net written premiums increased to 6.5% in Q4 2023, compared to 2.9% at the end of 2022. The return on average assets increased to 0.3% in Q4 2023 compared to the 0.1% at the of the previous year.