Workers warn of additional walkouts unless demands are met
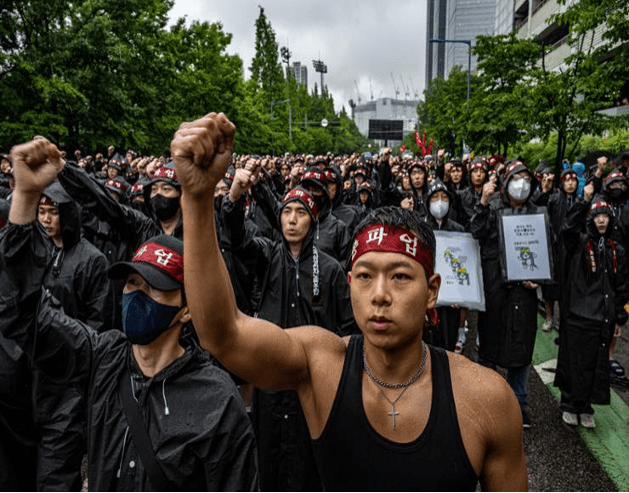
Members of the National Samsung Electronics Union stage a rally near the company's Hwaseong Campus in Gyeonggi Province, Monday, beginning a three-day strike. Korea Times photo by Shim Hyun-chul By Nam Hyun-woo The biggest labor union at Samsung Electronics initiated a three-day strike on Monday, threatening to disrupt the company's chip manufacturing lines unless management agrees to a wage hike and higher incentives. This marks the first strike by unionized workers in the tech giant's 55-year history. The National Samsung Electronics Union (NSEU) claimed that about 4,000 unionized workers from Samsung's plants nationwide participated in a rally at the company's Hwaseong Campus in Gyeonggi Province. Police estimated that approximately 3,000 union members were present at the rally. According to its own survey, the union reported that a total of 6,540 members expressed their intention to participate in the strike. They emphasized that disruptions in manufacturing are anticipated, with over 5,000 members from facility, manufacturing, and development divisions joining the strike. The comments seem to address market expectations that the walkout is unlikely to cause significant disruptions in the chipmaker's operations, largely because most manufacturing lines are automated. The union said that it may launch another strike for an undetermined period, unless management responds to the union’s demand. Since January, the union has been pressing management for a higher wage increase rate for all members, fulfillment of promises regarding paid leave, and improvements to incentive criteria. With negotiations at an impasse, the union announced on May 29 that it would launch a strike. The NSEU has some 30,000 members, accounting for 24 percent of all Samsung employees. Among the union members, about 80 percent work at the device solutions division, which manufactures semiconductors.
Exclusive: India's Paytm gets government panel nod to invest in payments arm, sources say
NEW DELHI, July 9 (Reuters) - India's beleaguered Paytm (PAYT.NS), opens new tab has secured approval from a government panel that oversees investments linked to China to invest 500 million rupees ($6 million) in a key subsidiary, three sources with direct knowledge of the matter said. The approval, which still has to be vetted by the finance ministry, will remove the main stumbling block to the unit, Paytm Payment Services, resuming normal business operations. Paytm Payment Services is one of the biggest remaining parts of the fintech firm's business, accounting for a quarter of consolidated revenue in the financial year ended March 2023. A separate unit, Paytm Payments Bank, was wound down this year by order of the central bank due to persistent compliance issues, triggering a meltdown in Paytm's stock. The government panel had earlier held back approval due to concerns about the 9.88% stake in Paytm held by China's Ant Group. India has intensified scrutiny of Chinese businesses since a 2020 border clash between the two countries. All in all, Paytm has been waiting for the nod from the government panel for about two years and without it, it would have had to also wind down its payment services business, which was forbidden from taking on new customers in March 2023. Once the approval has been formalised, it will be able to seek a so-called "payment aggregator" licence from the Reserve Bank of India. The sources, two of whom are government sources, declined to be identified as the decision has not been formally announced. India's foreign, home, finance and industries ministries, whose representatives sit on the panel, did not reply to emails seeking comment. A Paytm spokesperson said the company does not comment on market speculation. "We will continue to make disclosures in compliance with our obligations under the SEBI Regulations, and will inform the exchanges when there is any new material information to share," the spokesperson said.
Gold, silver caught in downdraft of broad commodity market sell off
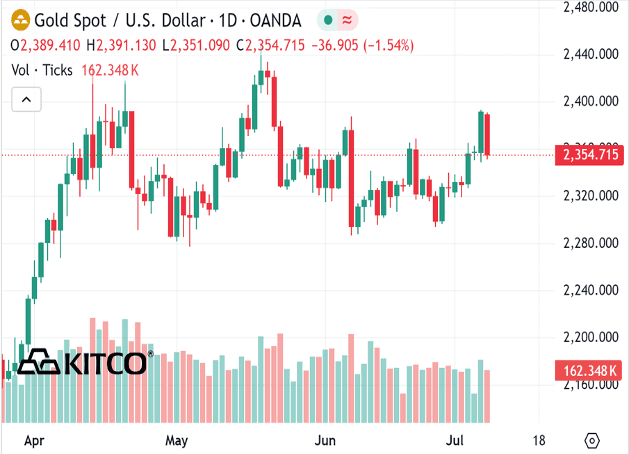
(Kitco News) - Gold and silver prices are sharply lower in midday U.S. trading Monday, on heavy profit-taking from the shorter-term futures traders after recent good price advances. The selling pressure today across most of the raw commodity spectrum is also keeping the precious metals bulls on the sidelines to start the trading week. August gold was last down $37.50 at $2,360.10. September silver was down $0.849 at $30.85. U.S. stock indexes mixed but near their record highs scored last week. The rallying stock market is a bearish element for the gold and silver markets, from a competing asset class perspective. The key U.S. data points of the week include Fed Chairman Powell’s speeches to the U.S. Congress on Tuesday and Wednesday, and the consumer and producer price indexes on Thursday and Friday, respectively. The key outside markets today see the U.S. dollar index slightly higher. Nymex crude oil prices are lower and trading around $82.25 a barrel. The benchmark 10-year U.S. Treasury note yield is presently 4.288%. Technically, August gold bulls have the overall near-term technical advantage. Bulls’ next upside price objective is to produce a close above solid resistance at the June high of $2,406.70. Bears' next near-term downside price objective is pushing futures prices below solid technical support at $2,300.00. First resistance is seen at $2,382.60 and then at $2,400070. First support is seen at $2,350.00 and then at last week’s low of $2,327.40. Wyckoff's Market Rating: 6.0. September silver futures bulls have the overall near-term technical advantage. Silver bulls' next upside price objective is closing prices above solid technical resistance at the May high of $33.05. The next downside price objective for the bears is closing prices below solid support at the June low of $28.90. First resistance is seen at $31.00 and then at $31.50. Next support is seen at Friday’s low of $30.45 and then at $30.00. Wyckoff's Market Rating: 6.5. (Hey! My “Markets Front Burner” weekly email report is my best writing and analysis, I think, because I get to look ahead at the marketplace and do some market price forecasting. Plus, I’ll throw in an educational feature to move you up the ladder of trading/investing success. And it’s free! Email me at jim@jimwyckoff.com and I’ll add your email address to my Front Burner list.)
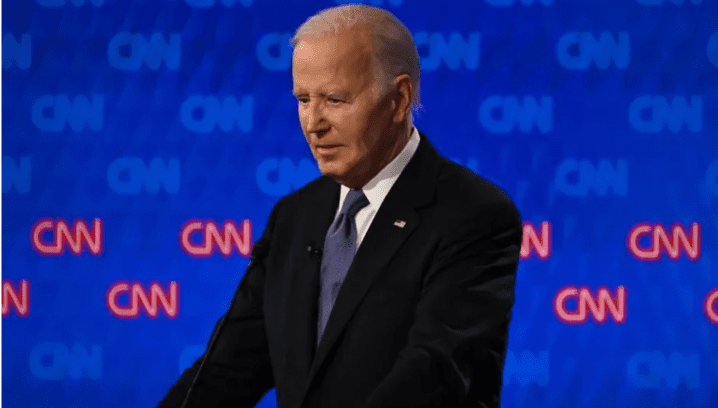
Biden accelerated aging over the past year!
n a recent interview with ABC, US President Joe Biden said he had no intention of dropping out of the race, blaming his poor debate performance on a cold. He also insisted he was "still in good shape" and would remain in the race, saying only "Almighty God" could pull him out. An insider who has worked with Mr. Biden for a long time said that signs of aging had become apparent over the past year, but that Mr. Biden's team had failed to address it. Biden's televised debate performance heightened concerns about an already slow-moving issue. Mr. Biden's advisers have long dodged questions about his age. But now they acknowledge that Biden's aging is an undeniable fact. The debate forced the president to more openly acknowledge the limitations of his age, which he had previously largely dismissed. But they have only taken superficial measures and have not fundamentally solved the problem. They replaced the long staircase that Mr. Biden used to board Air Force One with a shorter one; Assistants often accompanied him in public to make his stiff gait less noticeable; While he has a busy schedule, aides have arranged for buffer time, such as long weekends at his homes in Wilmington and Rehoboth Beach, Delaware, or extended stays at Camp David, a Maryland resort, to rest after a "grueling" stretch of travel. Under the authority of one of his top advisers, Anita Dunn, Mr. Biden's public interactions -- especially with reporters -- were severely limited. Even at major events with Democrats or other supporters, the White House sometimes limits the amount of time Biden can spend with the audience, two people familiar with the matter said. As a protective response, designed to protect their longtime boss.
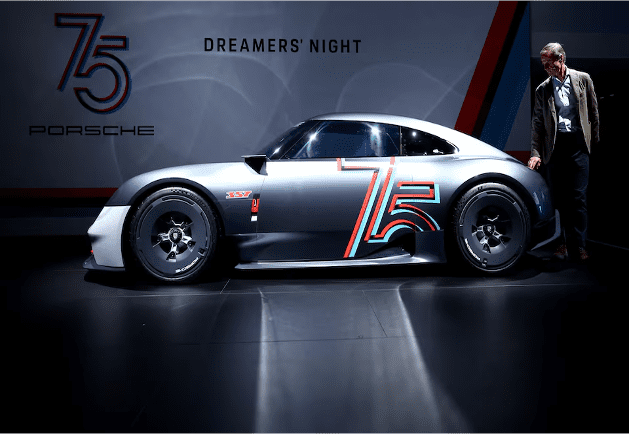
Porsche AG reports sharp fall in China deliveries
July 9 (Reuters) - German sportscar maker Porsche (P911_p.DE), opens new tab said on Tuesday that global vehicle deliveries were down 7% in the first half of the year compared to the same period in 2023, primarily driven by a 33% year-on-year drop in China. Porsche, majority-owned by Volkswagen (VOWG_p.DE), opens new tab, is highly exposed to the EU-China tariff tensions, with deliveries to China accounting for nearly 20% of global deliveries. An HSBC analyst pointed to weakness in the European car market, saying that "the market is, understandably, worried about China pricing weakness and the prospect of needing to pay dealer compensation." Overall, Porsche delivered 155,945 cars worldwide during the first six months of the year. In North America, deliveries were down 6% year-on-year. Meanwhile, in Porsche’s home market of Germany, deliveries increased by 22% to 20,811 vehicles.